
Polymarket’s “Will China invade Taiwan by end of 2026?” contract trades at 3.85¢ on the Yes — a 3.85% market-implied probability — while an estimate built from US intelligence assessments, Taiwan’s detection data, PLA command turmoil and the strait’s seasonal weather windows puts the true number nearer 1.0%, an edge of roughly 2.85 percentage points (pp) on the No side (Polymarket gamma API, 09:50 UTC, August 22, 2026).
The most important input is tempo: Taiwan’s Ministry of National Defense logged 1,334 PLA aircraft sorties in the first half of 2026, less than half the same period of 2025 and the lowest first-half figure since 2023. Militaries escalate before they invade; this one is de-escalating. What follows walks the resolution language, the term structure across Polymarket’s Taiwan contracts, the case for and against, and the signals that would break the read.
The Bet at a Glance:
• Market: “Will China invade Taiwan by end of 2026?” on Polymarket — market ID 567621, opened July 24, 2025
• Price: Yes 3.85¢ / No 96.15¢ = 3.85% market-implied probability; best bid 3.8¢, best ask 3.9¢ — Polymarket gamma API, 09:50 UTC, August 22, 2026
• Liquidity: $39.94m lifetime volume, $589,174 resting liquidity, $55,309 traded in 24 hours — Polymarket gamma API
• Our estimate: 1.0% over the remaining 131 days — hazard-rate model from ODNI, Taiwan MND and seasonal-window data
• Edge: roughly 2.85pp, with Yes trading at about 3.9 times our estimate — our model
• Catalyst: resolution 23:59 ET, December 31, 2026; last viable landing month is October — War on the Rocks, June 5, 2023
• Disconfirmation: visible sealift mobilisation — ferry requisition, reserve call-up, evacuation of PRC nationals — voids the estimate within days
Methodology: how the 1.0% estimate was built
The estimate is a hazard-rate model over the 131 days between August 22 and December 31, 2026. The historical anchor: the last PRC seizure of territory administered by the Republic of China was the amphibious assault on the Yijiangshan Islands in January 1955, 859 months ago. Zero qualifying events in 859 months puts the 95% upper bound on the monthly hazard at 0.35% under the rule of three, compounding to roughly 1.5% across a 4.3-month window — already below the market price. That baseline is then set against intent evidence from the US Intelligence Community and tempo evidence from Taiwan MND daily releases compiled by the Taiwan Security Monitor, then adjusted for seasonality and the offshore-island branch.
The caveats are real. Strategic surprise is precisely the scenario that defeats trend extrapolation. The base rate rests on one event across seven decades. The seasonal haircut is a judgement, not a measurement. And the offshore-island branch rests on resolution text never yet tested.
What this contract actually resolves on — and what it does not
This is the part most traders skip. It reads: “This market will resolve to ‘Yes’ if China commences a military offensive intended to establish control over any portion of the Republic of China (Taiwan) by December 31, 2026, 11:59 PM ET.” It adds that ROC-administered territory “including any inhabited islands will qualify, however uninhabited islands will not qualify.”
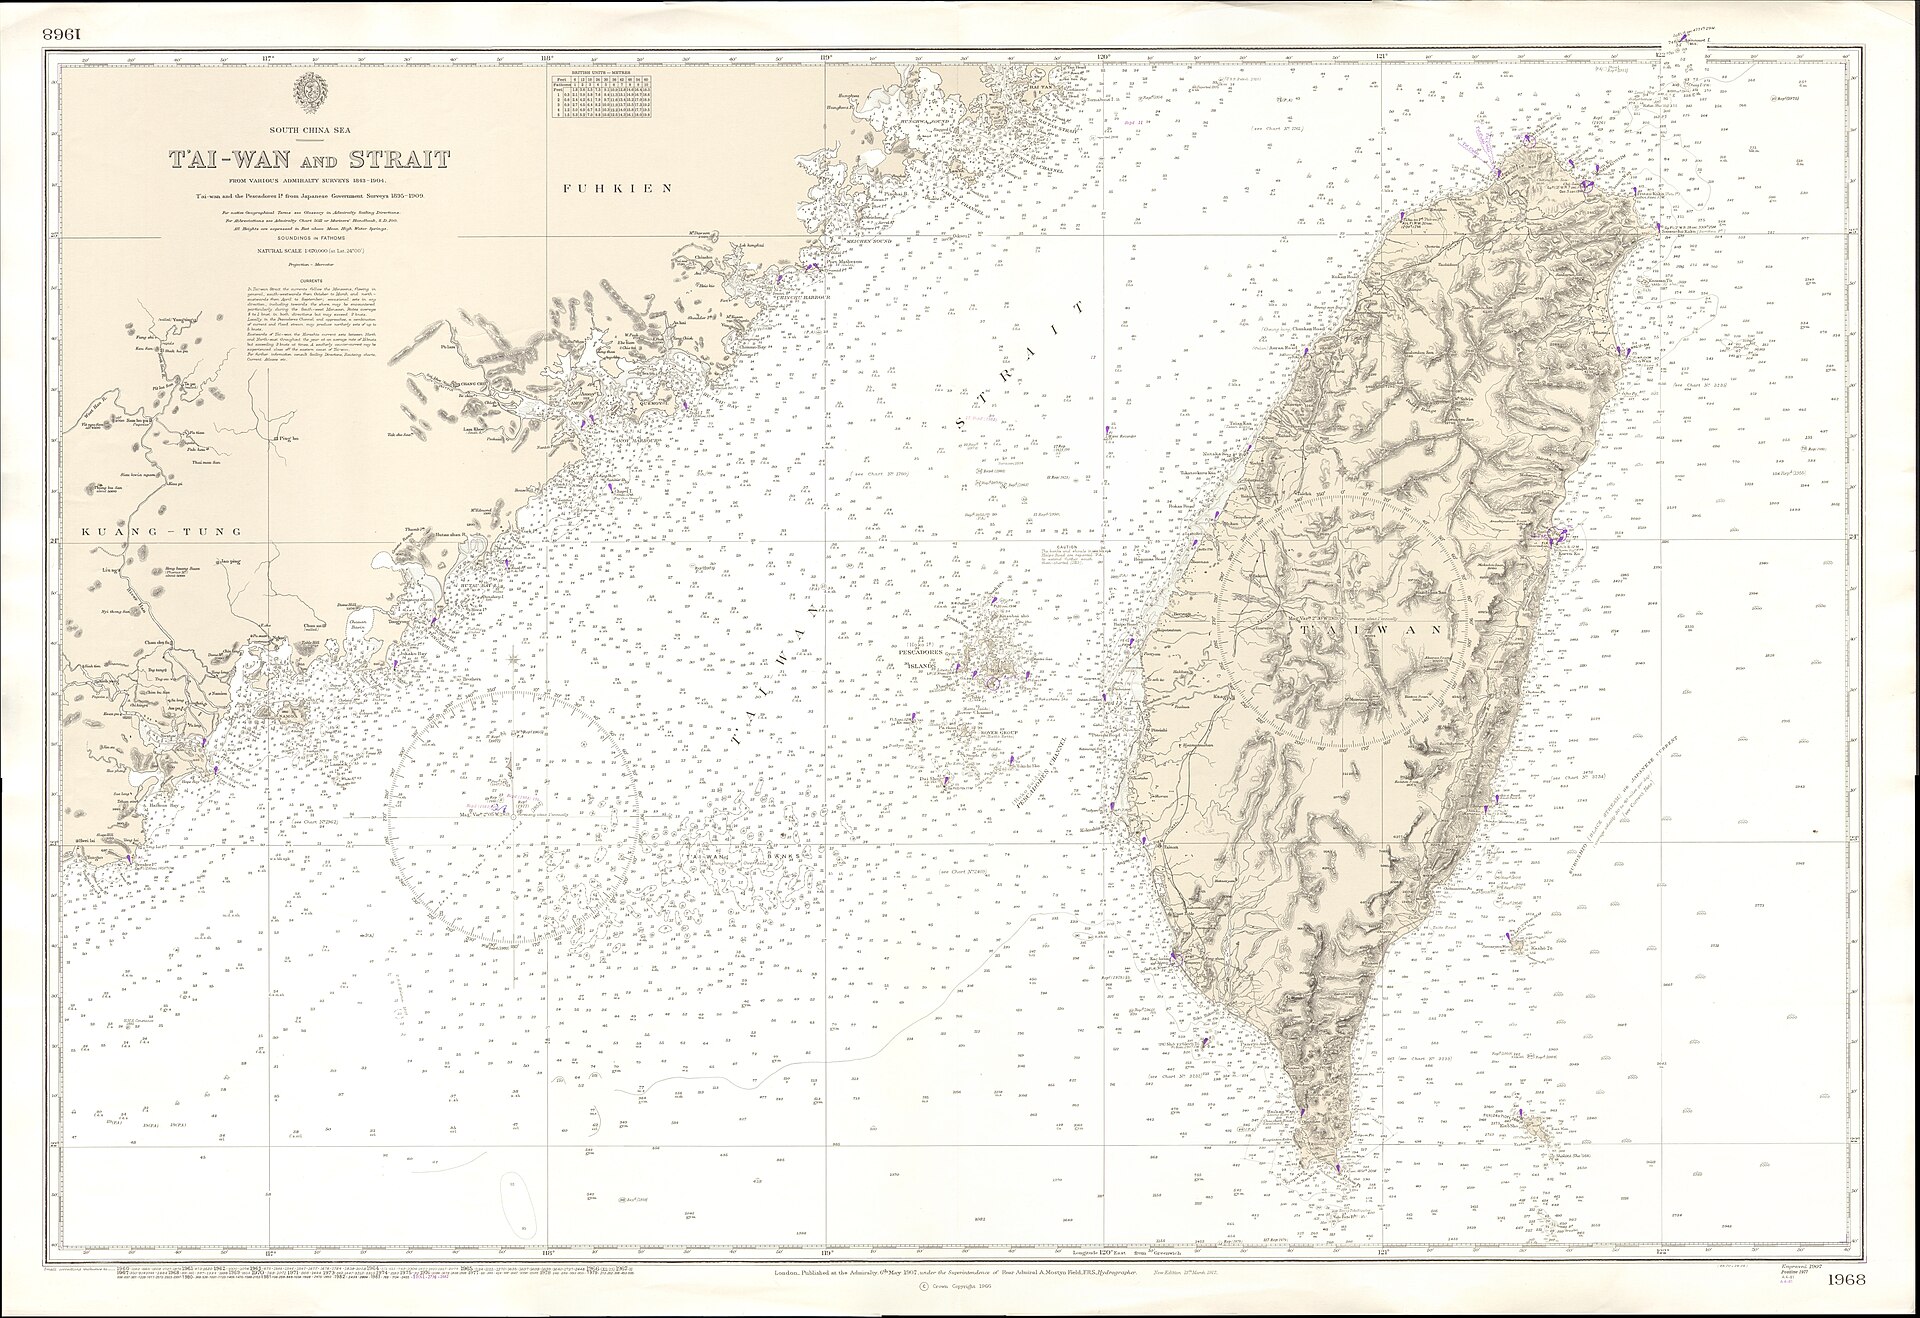
Two consequences follow, in opposite directions. The contract is broader than “invade Taiwan” suggests: it requires no landing on the main island and no success, only that an offensive commences. An assault on Kinmen — six miles off the Chinese coast, with a substantial civilian population — would qualify. So, arguably, would one on Pratas (Dongsha), garrisoned by roughly 300 Taiwanese coast guard personnel but with no civilian residents.
It is also narrower than “something serious happens in the strait.” A blockade does not qualify — it controls traffic, not territory, and Polymarket runs a separate blockade contract at 6.5¢ on $261,224 of volume. Nor does a quarantine, missile strikes without a territorial objective, air defence identification zone (ADIZ) incursions, median-line crossings, cable sabotage or cyber operations, all recurring through 2026 without moving this market. That matters, because the scenarios the literature considers most likely are the excluded ones. The Center for Strategic and International Studies (CSIS) draws the line:
“A quarantine is more feasible for China and more likely than an invasion or blockade in the near term.”
— Bonny Lin, Director of the China Power Project and Senior Adviser, Center for Strategic and International Studies (CSIS)
CSIS defines a quarantine as “a law enforcement–led operation to control maritime or air traffic within a specific area while a blockade is foremost military in nature.” Neither establishes control over territory. Anyone buying Yes expecting Beijing to squeeze Taiwan before year-end holds a contract that will not pay on the most probable version of that squeeze.
The price: a term structure that does not hold together
Polymarket lists several contracts covering escalation across the strait, and reading them together is more informative than any one alone. Converting each into an implied monthly hazard rate exposes an inconsistency.
| Contract | Price (Yes) | Implied probability | Window | Hazard per month |
|---|---|---|---|---|
| Invade Taiwan by Sep 30, 2026 | 0.85¢ | 0.85% | 39 days | 0.66pp |
| Invade Taiwan by end of 2026 | 3.85¢ | 3.85% | 131 days | 0.90pp |
| Invade Taiwan by Dec 31, 2027 | 12.5¢ | 12.50% | 496 days | 0.77pp |
| China–Taiwan military clash before 2027 | 7.35¢ | 7.35% | 131 days | 1.71pp |
| Blockade of Taiwan in 2026 | 6.5¢ | 6.50% | 131 days | 1.51pp |
| Implied Q4 2026 residual | 3.00¢ | 3.00% | 92 days | 1.00pp |
| Implied full-year 2027 residual | 8.65¢ | 8.65% | 365 days | 0.72pp |
Source: Polymarket gamma API snapshot, 09:50 UTC, August 22, 2026. Hazard rates are our arithmetic: implied probability divided by window length in months.
Subtract the September 30 contract from the end-2026 contract and the book prices a 3.00% chance a qualifying offensive begins between October 1 and December 31 — 1.00pp a month. Subtract end-2026 from end-2027 and the whole of 2027 prices at 8.65pp across 12 months, or 0.72pp per month. The same order book prices the final quarter of 2026 at a monthly rate 39% higher than the entirety of 2027 — the year Xi Jinping reportedly told the PLA to be ready.
That would be defensible if Q4 2026 were favourable. It is the opposite. In War on the Rocks, Marine Corps logistics officer Benjamin Van Horrick set out the calendar: “March through May is one of two ideal windows of meteorological opportunity for cross-strait amphibious operations, with the other occurring in September and October,” while “from June through August, and then again between November and February, the weather in the Taiwan Strait, specifically frequent monsoons, typhoons, and prohibitive sea-states, make amphibious operations extremely difficult.” Two of the residual’s three months sit in the prohibitive band.
Is the Yes side at 3.85¢ value? On the evidence available on August 22, 2026, no — and the reason is arithmetic rather than opinion. Only about 40 of the 131 remaining days fall inside a viable amphibious window, so effective exposure is closer to five weeks than four and a half months. Against that, the market’s own term structure prices the least viable quarter of the year at the highest monthly hazard it quotes, 39% above the rate it assigns the readiness year Beijing itself nominated. The US Intelligence Community’s published position is that no invasion is planned for 2027 at all, and Taiwan’s detection data shows PLA air activity at less than half its 2025 rate. Every observable input points one way; the price does not follow. The gap is roughly 2.85pp.
The case that 3.85¢ is too high
Intent. The Office of the Director of National Intelligence released its 2026 Annual Threat Assessment on March 18, 2026, and the language is unusually direct: the Intelligence Community assesses that Chinese leaders “do not currently plan to execute an invasion of Taiwan in 2027, nor do they have a fixed timeline for achieving unification.” For Yes to resolve, the IC must be wrong and the operation must occur earlier than the year it explicitly ruled out.
Tempo. Coercion has slackened rather than intensified across 2026 — the wrong signature for a state 131 days from a landing.
| Metric | 2026 figure | 2025 comparison | Change |
|---|---|---|---|
| PLA aircraft sorties, January–June | 1,334 | Over 2,668 | Over −50% |
| PLA aircraft sorties, May | 274 | 458 | −40% |
| ADIZ incursions, July | 190 | Over 380 | Over −50% |
| Monthly sortie range, January–May | 173 to 274 | 458 peak in May 2025 | −40% to −62% |
Sources: Taiwan MND daily releases compiled by the Taiwan Security Monitor, George Mason University; and the AEI/ISW China–Taiwan Update, August 7, 2026. The 2025 columns express reported “less than half” relationships as bounds.
Those 1,334 first-half sorties are the lowest since 2023. Equally telling is the absence: through August 2026 the PLA has announced no named large-scale exercise on the Joint Sword or Strait Thunder pattern. Strait Thunder-2025A, launched April 2, 2025, carried a designation signalling more to follow. The spectacle then stopped.
Command. Xi Jinping’s purge has run through the formations that would execute a landing. Central Military Commission vice chairman He Weidong and Political Work Department director Miao Hua were removed at the Fourth Plenum in October 2025; Zhang Youxia and Liu Zhenli followed in January 2026; on June 26, 2026 the NPC Standing Committee stripped 13 delegates including six PLA generals. Both He and Miao rose through the 73rd Group Army, the Fujian formation expected to spearhead amphibious operations against Taiwan.
Absent indicators. An assault on this scale cannot be concealed: it needs weeks of visible preparation — ferry requisition, medical stockpiling, reserve mobilisation, port closures. None has been reported. Even a decision taken today would push the earliest plausible launch into October, a single viable month.
The case that the market is right
A 2.85pp edge on a 3.85¢ contract is not the same as an opportunity, and four reasons suggest the price is doing its job.
First, it is not purely a forecast. On $39.94m of volume, a meaningful share of the Yes side is portfolio insurance against a tail event that would reprice global equities, semiconductors and shipping. Insurance trades above actuarial fair value by construction — that is what a premium is. Measuring a hedging instrument against a forecast and calling the gap an error mistakes the instrument for a poll.
Second, the No side’s arithmetic is unflattering. No at 96.15¢ returns 4.00% gross if held to resolution, roughly 11.4% annualised, capital committed for 131 days — thin compensation for a small but genuine risk of total loss whose failure mode coincides with a global dislocation.
Third, deep out-of-the-money contracts on catastrophic tails have a documented price floor. Longshot bias, the cost of capital for shorting them, and persistent hedging demand keep such markets sticky in the 2–5¢ band. Being right about fair value does not mean the price converges to it.
Fourth, falling tempo cuts both ways. Fewer sorties can mean reduced intent — or resources shifted into preparation away from the public theatre of ADIZ patrols. The Taiwan Security Monitor notes “air activity responds to political events” while “naval presence serves as a consistent baseline,” and naval detections held steady at 6.7 vessels per day in May 2026. Quiet is not automatically reassuring. The loudest voice on that side is the officer who would have to fight:
“Their leader has declared that by 2027 they shall be ready to execute a unification by force.”
— Admiral Samuel J. Paparo, Commander, US Indo-Pacific Command, aboard USS Theodore Roosevelt (Hawaii News Now, August 11, 2026)
Paparo has consistently characterised PLA activity as rehearsal rather than routine training, and in the same remarks noted China is “building 800+ missiles per year.” That is a readiness benchmark, not a launch date — but the capability curve moves one way while the price moves the other.
What would make the No side wrong? A break in the indicator chain, not a change in rhetoric. Beijing has escalated verbally many times without moving hardware, and the market has correctly ignored it every time. What has never appeared in 2026 is the logistical signature of an amphibious operation: civilian ferry requisition, hospital and blood-bank surge orders, reserve mobilisation notices, Fujian port closures, and the quiet withdrawal of PRC nationals from exposed jurisdictions. If two or more surface together, the 1.0% estimate is void within days and the correct response is to stop modelling and start watching. A second, separate failure mode is definitional rather than military: an armed seizure of Pratas or a Kinmen-adjacent islet could resolve this contract Yes on wording alone, with nothing resembling the invasion the headline implies, and at a fraction of the cost.
Where this bet breaks
The lean against Yes at 3.85¢ rests on assumptions that can fail. It breaks if any of these fire:
- Sealift mobilisation becomes visible. Requisition of civilian roll-on/roll-off ferries, Fujian port closures, or reserve call-up notices would signal the decision has been taken. The estimate assumes their absence is informative; their appearance destroys that assumption.
- An offshore-island incident escalates past law enforcement. China Coast Guard vessels staged repeated standoffs near Pratas through May and June 2026. If PLA Navy units replace them, the cheapest path to a Yes resolution — a limited island seizure — moves from theoretical to live, and it is far less weather-constrained than a main-island crossing.
- The price moves through 6¢ on volume. Above roughly 6¢ the market is pricing something the public record does not contain, and the inference is that informed flow knows more than this model does.
- Sortie counts revert above the 2025 baseline. A month above 458 sorties, or a named exercise on the Joint Sword pattern, reverses the tempo argument and removes the estimate’s main pillar.
What to watch between now and December 31
Three calendars matter. The first is meteorological: October is the last month inside a viable amphibious window, and once the northeast monsoon establishes in November the physical constraint does most of the work. Absent news, expect Yes to decay through the fourth quarter on time value alone.
The second is the data release. Taiwan’s MND publishes daily detection figures and the Taiwan Security Monitor aggregates them; the August, September and October totals are the highest-frequency read on whether the slowdown holds. A month above 300 sorties would be the year’s first genuine deviation.
The third is political. Taiwan’s Supreme Court has categorised the Chinese Communist Party and the Taiwan Affairs Office as “foreign hostile forces” under the Anti-Infiltration Act; Beijing’s response is an escalation vector worth tracking. Watch too for any Polymarket clarification on whether Pratas satisfies the “inhabited” test.
TL;DR
Polymarket’s “Will China invade Taiwan by end of 2026?” trades at 3.85¢ Yes — a 3.85% implied probability — on $39.94m of volume. Our hazard-rate estimate, built from the ODNI’s March 2026 assessment that no invasion is planned even for 2027, PLA sorties running at less than half their 2025 rate, an ongoing purge of the commanders who would lead a landing, and a seasonal window that closes after October, is 1.0%. That is an edge of roughly 2.85pp. The read breaks the moment sealift mobilisation or reserve call-up becomes visible.
Frequently asked questions
What are the current Polymarket odds on China invading Taiwan in 2026?
As of 09:50 UTC on August 22, 2026, Yes trades at 3.85¢ against 96.15¢ on No, with a best bid of 3.8¢ and best ask of 3.9¢. On a prediction market the cents read directly as a probability, so 3.85¢ is a 3.85% implied probability. The contract has traded $39.94m in volume with $589,174 of resting liquidity, and resolves 23:59 ET on December 31, 2026.
Does a blockade or quarantine of Taiwan resolve this market Yes?
No. The resolution requires that China “commences a military offensive intended to establish control over any portion of the Republic of China (Taiwan).” A blockade controls traffic, not territory, and Polymarket runs a separate blockade contract at 6.5¢. A quarantine — law-enforcement-led rather than military, per CSIS — falls outside both, as do missile strikes without a territorial objective, ADIZ incursions, median-line crossings, cable sabotage and cyber operations. This is the most common misreading of the contract.
Would an attack on Kinmen or Pratas count?
Kinmen almost certainly would. The resolution states ROC-administered territory “including any inhabited islands will qualify, however uninhabited islands will not qualify,” and Kinmen holds a substantial civilian population six miles off the Chinese coast. Pratas (Dongsha) is less clear: garrisoned by roughly 300 Taiwanese coast guard personnel but with no permanent civilian residents. That ambiguity is the fattest part of the Yes tail and the reason our estimate is 1.0% rather than lower.
Why is the estimate 1.0% rather than the market’s 3.85%?
Four inputs. The ODNI’s 2026 Annual Threat Assessment states Chinese leaders do not plan to invade in 2027 and have no fixed unification timeline. PLA aircraft sorties ran to 1,334 in the first half of 2026, the lowest since 2023. The high command has been purged of the officers who would lead an amphibious operation, including two Central Military Commission vice chairmen. And only about 40 of the 131 remaining days fall inside a viable weather window.
Related analysis: the US–Iran nuclear deal contract at 11.5¢, the French election 2027 market, the NYC mayor exit market at 4.5¢, and the Fed September 2026 contract. Market data: Polymarket gamma API; seasonal analysis: War on the Rocks and the Council on Foreign Relations.
This article is informational analysis only and is not betting or financial advice. Odds and prediction-market prices move constantly; every price quoted is a timestamped snapshot, not a live line. There is no such thing as a guaranteed bet — past results and model estimates do not guarantee outcomes. Do your own research.
Gambling carries financial risk and can be addictive. 18+ / 21+ depending on jurisdiction. Never bet more than you can afford to lose. If you or someone you know needs help, visit GamCare (UK), call 1-800-GAMBLER (US), or see our Responsible Gambling page.